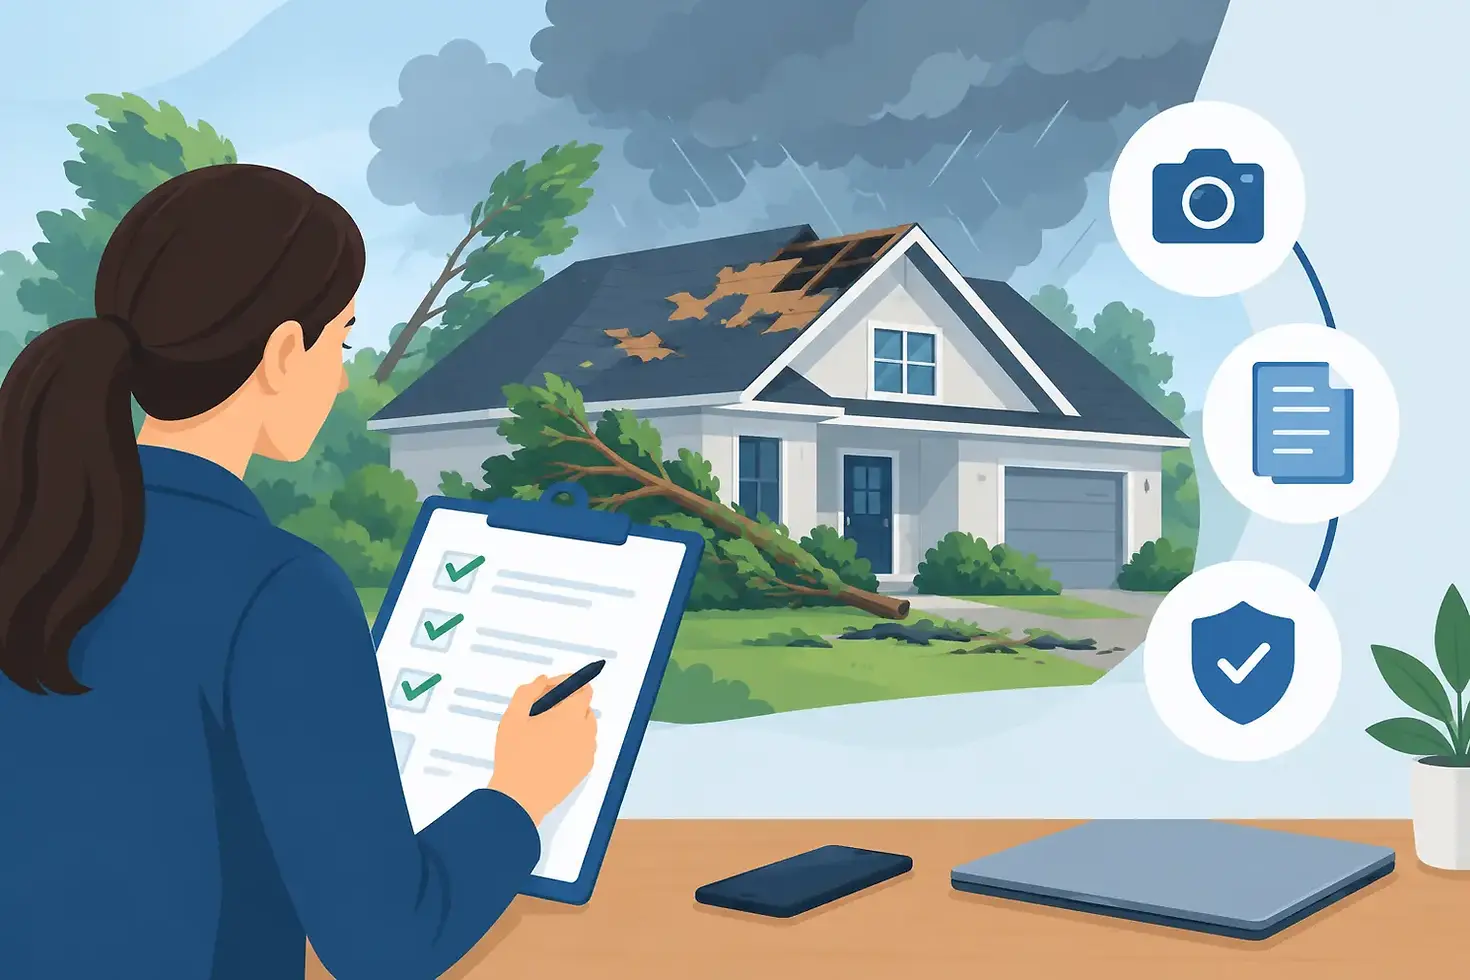
How to File a Storm Claim Without Missing Steps
A North Georgia storm can leave behind more than branches in the yard. Hail bruises shingles without always leaving an obvious leak, wind lifts roof materials at the edges, and clogged or damaged gutters can send water where it does not belong. Knowing how to file a storm claim before the evidence disappears can protect both your home and your ability to receive the coverage your policy provides.
The goal is not to make the process more complicated than it needs to be. It is to document the facts, prevent additional damage, report the loss promptly, and make informed decisions while your insurer evaluates the claim. A dependable local contractor can help you understand the damage, but the final coverage decision always belongs to your insurance carrier.
Start With Safety and Emergency Protection
Do not climb onto a roof after a storm. Wet shingles, loose debris, hidden structural damage, and downed power lines create real hazards. Start from the ground and look for visible warning signs: missing or lifted shingles, bent flashing, fallen limbs, damaged gutters, torn screens, broken siding, or water entering the attic or ceiling.
If water is actively coming into the home, take reasonable steps to limit further damage. Move furniture and valuables, place containers under drips, and use a tarp or temporary covering when it can be done safely by a qualified professional. Most insurance policies require homeowners to mitigate additional damage after a loss. That does not mean you should begin a major repair before the insurer has a chance to inspect it. It means protecting the property from getting worse.
Keep receipts for emergency work, tarping, water extraction, and materials purchased to protect the home. Take photos before and after temporary repairs when possible. Those records can help explain why the work was necessary.
Document the Damage Before Cleanup Begins
Storm evidence can disappear quickly. Debris gets hauled away, hail marks become harder to identify, and a small leak may dry up temporarily. Thorough documentation gives your claim a clear starting point.
Take wide photos of every affected area, then close-up photos of specific damage. Include the roofline, gutters, downspouts, siding, fencing, deck surfaces, exterior HVAC equipment, windows, and any interior staining or moisture. If hail fell, photograph the hail itself beside a common object for size reference. Video can also be useful for showing the overall condition of the property.
Write down the date and approximate time of the storm, along with what you observed. For example, note high winds, hail size, tree impact, water intrusion, or a sudden ceiling stain after rainfall. Do not throw away damaged materials, such as a fallen shingle or bent gutter section, until your insurer or contractor advises you that it is appropriate.
A professional storm inspection adds another layer of documentation. Roof damage is not always visible from the ground, and not every mark is storm-related. An honest inspection should distinguish recent storm damage from normal aging, installation issues, and pre-existing wear. That clarity matters because filing a claim without a covered loss may not be the right choice for every homeowner.
Review Your Policy and Compare the Deductible
Before calling the insurance company, locate your homeowners policy or pull it up through your insurer’s portal. Look for your deductible, the type of roof coverage you carry, and whether your policy has a separate wind or hail deductible. In Georgia, those details can vary significantly from one policy to another.
A deductible is the portion of a covered loss you are responsible for paying. If repair costs are close to or below that amount, filing a claim may not make financial sense. If damage is more extensive, a claim may be appropriate, particularly when the roof, gutters, or other exterior systems require substantial restoration.
Pay attention to whether your policy pays replacement cost value or actual cash value. Replacement cost coverage generally accounts for the cost to replace covered materials, subject to policy terms and depreciation rules. Actual cash value coverage factors in age and wear, which can reduce the payment. Your insurer can explain your specific policy, and a qualified contractor can help prepare an accurate scope of visible damage.
How to File a Storm Claim With Your Insurer
Once you have documented the condition of the property and understand your deductible, contact your insurance carrier directly. Most insurers allow claims by phone, online portal, or mobile app. Report the date of loss, describe the storm event and affected areas, and ask for a claim number.
Keep your description factual. You do not need to diagnose the roof or estimate the full cost of restoration. Explain what you saw: hail struck the property, wind removed shingles, a tree limb damaged the roof, or water entered through a newly damaged area. Avoid guessing about the cause if you are not certain.
During that first conversation, ask about the next steps, the adjuster’s contact information, expected inspection timing, and whether the carrier has requirements for temporary repairs. Record the date, the representative’s name, and the claim number in one place. Email follow-ups are helpful because they create a written record.
Do not sign an assignment of benefits or authorize permanent work before you understand what you are agreeing to. A reputable contractor can inspect damage, provide a written estimate, meet with the adjuster when requested, and complete approved repairs. They should not pressure you to sign paperwork you have not had time to review or promise an outcome they cannot control.
Prepare for the Adjuster Inspection
The adjuster’s inspection is a key point in the process. Make sure they can safely access the property and that gates, attic access, and relevant areas are available if needed. Have your photos, notes, temporary repair receipts, and contractor inspection findings ready.
It is often helpful to have your roofing contractor present during the appointment. This allows the contractor to point out documented damage, explain construction details, and compare the insurer’s scope with the work needed to restore the home properly. Cumming Roofing Co regularly helps homeowners communicate clearly during this stage, especially when storm damage involves roofing, gutters, and related exterior repairs.
The adjuster may approve the claim, deny it, or issue an estimate that does not include every item identified during inspection. None of those outcomes should be treated as the final word without review. Read the estimate carefully. Look at line items for shingles, underlayment, flashing, ventilation, drip edge, gutters, interior repairs, and code-related requirements where applicable.
If the Estimate Is Too Low or the Claim Is Denied
An estimate may need supplementation if additional covered damage is discovered during repairs or if the initial scope missed necessary materials and labor. This is common when damage is concealed beneath shingles or when matching, flashing, and code requirements affect the proper repair method.
Ask your contractor to provide clear documentation for any differences. Photos, measurements, manufacturer requirements, and a detailed written scope are more useful than broad statements that the estimate is inadequate. Submit the information through the insurer’s preferred process and keep copies of all correspondence.
If your claim is denied, request the explanation in writing and compare it with your inspection documentation and policy language. A denial can be correct when damage is due to age, maintenance issues, or an excluded cause. But if you believe the inspection missed storm-related damage, you can ask the carrier to review additional evidence or request a reinspection. Stay professional, specific, and persistent.
Avoid the Mistakes That Create Delays
Claims tend to go more smoothly when homeowners avoid a few preventable problems. Waiting too long can make it harder to connect damage to a specific storm. Cleaning up before taking photos can remove useful evidence. Starting major repairs before documentation can create confusion about what the storm actually damaged.
Be cautious of contractors who appear immediately after a storm and insist you must sign that day. Local accountability matters. Look for a licensed and insured contractor with a physical presence in the area, clear written estimates, and the ability to explain the work in plain language. Never agree to a contractor covering or waiving your deductible. Your deductible is part of your insurance agreement, and handling it improperly can create serious problems.
Also remember that insurance proceeds are intended to restore covered damage, not to fund unrelated upgrades. If you decide to upgrade materials, add a new gutter system, or change the design of the roof, ask for a separate estimate that clearly shows the homeowner-paid portion.
Keep the Claim Organized Until Work Is Complete
Create a simple file for your claim. Keep the claim number, policy details, inspection reports, photos, estimates, receipts, adjuster correspondence, and payment records together. Insurers may issue payments in stages, particularly when depreciation is recoverable after work is completed. Your contractor should provide invoices and completion documentation that support the final payment process.
Before final payment, walk the property with your contractor. Confirm that roofing materials are installed correctly, flashing and vents are properly addressed, gutters drain as intended, debris is removed, and any agreed-upon repairs are complete. This is your home, and you deserve to understand what was repaired and why.
After a storm, quick action matters, but rushed decisions do not. Take photos, protect the property, report legitimate damage, and work with people who will explain the process honestly. A well-documented claim and quality restoration can help your home stand ready for the next North Georgia weather event.


Comments